Fees
Hidden credit card processing fees every merchant should know
8 min read
Quick answer
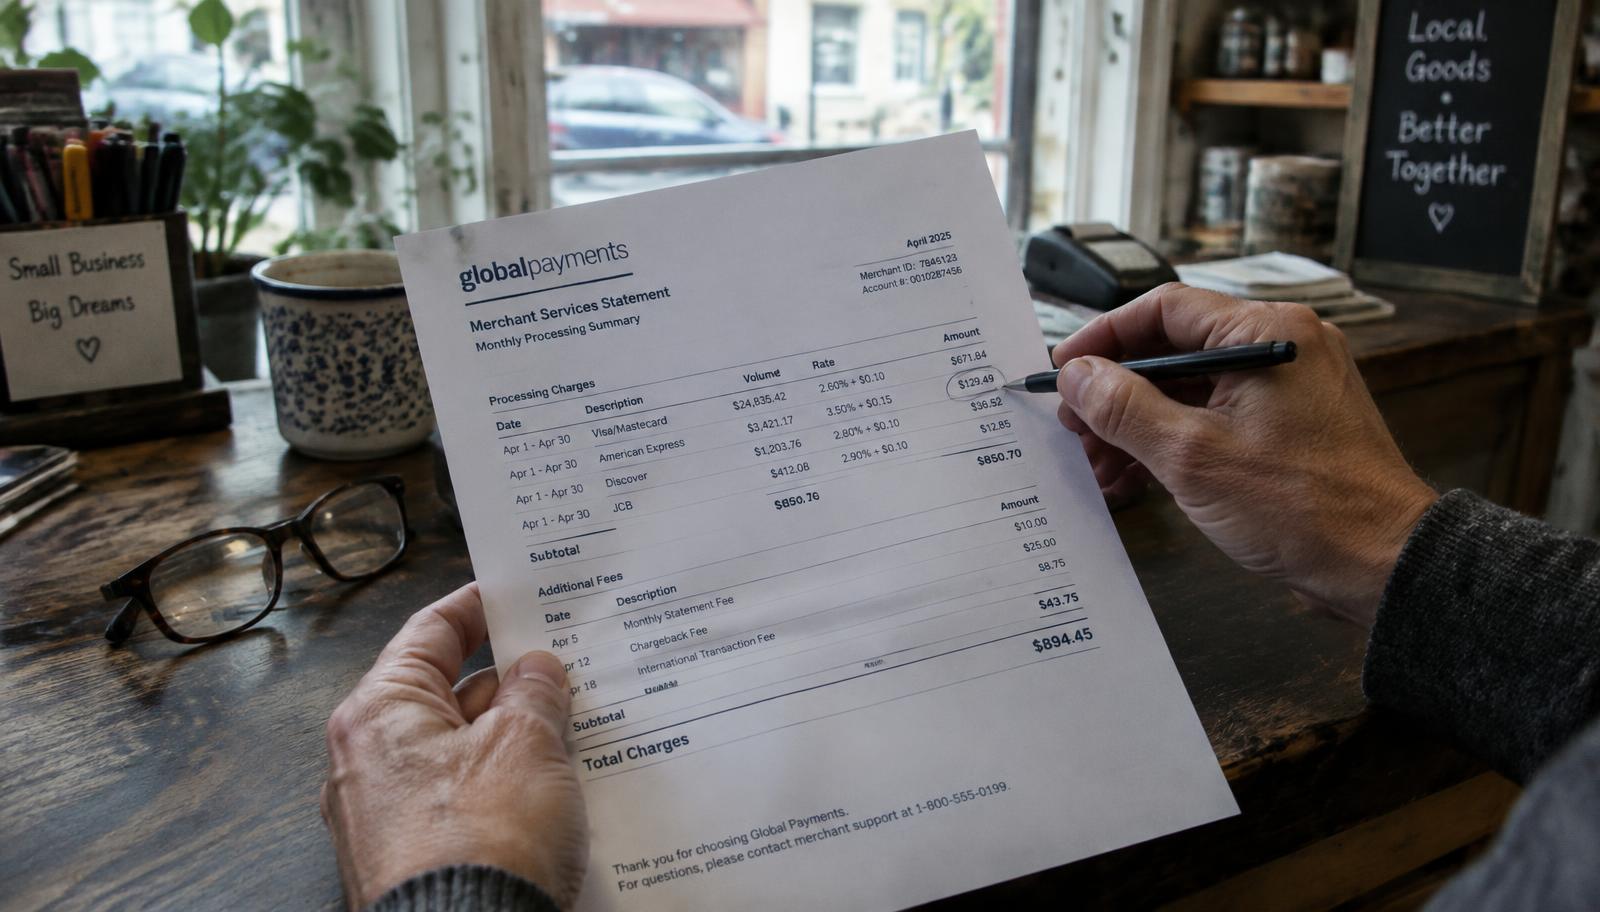
Hidden credit card processing fees are the extra charges buried in a merchant statement beyond the advertised rate, things like statement fees, PCI non-compliance fees, batch fees, annual fees, and gradual rate increases. They add up to real money every month, and most of them are either negotiable or avoidable with the right processor.
Key takeaways
- Your quoted 'rate' almost never matches your real cost, junk fees are added on top every month.
- PCI non-compliance fees ($20–$40/mo) disappear the moment you complete a short annual questionnaire.
- Batch fees, statement fees, and annual fees are pure profit for the processor and are almost always negotiable.
- Rate creep happens quietly over years, compare your rate every 12 months, not just at signup.
- Reading your statement line by line, or having someone else do it, is the fastest way to find savings.
Why your statement never matches the rate you were quoted
Almost every merchant we talk to was quoted a rate when they signed up, something like '1.79%' or 'as low as 2.6%.' Then the first real statement arrives and the actual cost is noticeably higher. That gap is almost never a mistake. It's a collection of extra line items that were never part of the sales pitch: statement fees, PCI fees, batch fees, annual fees, monthly minimums, and a rate that quietly creeps upward over time.
None of these fees are illegal, and some cover real costs. But many are pure markup with no real cost behind them, and processors count on merchants not reading past the total. Once you know what to look for, most of it is either avoidable or negotiable. For a full breakdown of how card fees are structured in the first place, see our guide to credit card processing fees explained.
The most common hidden fees
| Fee | Typical amount | What it's for | Can you avoid it? |
|---|---|---|---|
| Statement fee | $5 – $15/mo | Cost of producing your monthly statement | Often waivable, ask directly |
| PCI non-compliance fee | $20 – $40/mo | Charged if you haven't completed your PCI questionnaire | Yes, complete the questionnaire |
| Batch fee | $0.10 – $0.35 per batch | Charged each time you close out the day's transactions | Sometimes negotiable, rarely eliminated |
| Annual fee | $79 – $149/yr | A flat yearly charge, often unexplained | Frequently negotiable or waivable |
| Monthly minimum fee | $10 – $25/mo | Charged if your total processing fees don't hit a minimum | Avoidable with the right pricing plan |
| Regulatory/compliance fee | $3 – $10/mo | A processor-invented fee, not a card network requirement | Ask what it actually covers |
| Early termination fee | $95 – $500+ | Charged for leaving before your contract ends | Avoid by choosing month-to-month |
Rate creep: the fee you don't notice
The sneakiest cost isn't a line item at all, it's your effective rate slowly rising. A processor might raise your rate by a tenth of a percent every few months, buried in a notice you never opened, betting you won't compare your statement to what you signed up for. Over two or three years, a merchant doing $50,000 a month in card sales can end up paying hundreds of extra dollars a month without a single new fee appearing.
This is one reason flat-rate pricing looks simple but can cost more over time, while interchange-plus pricing keeps the markup visible and fixed. We compare the two in interchange-plus vs. flat-rate pricing.
How to actually read your statement
Start with the summary page
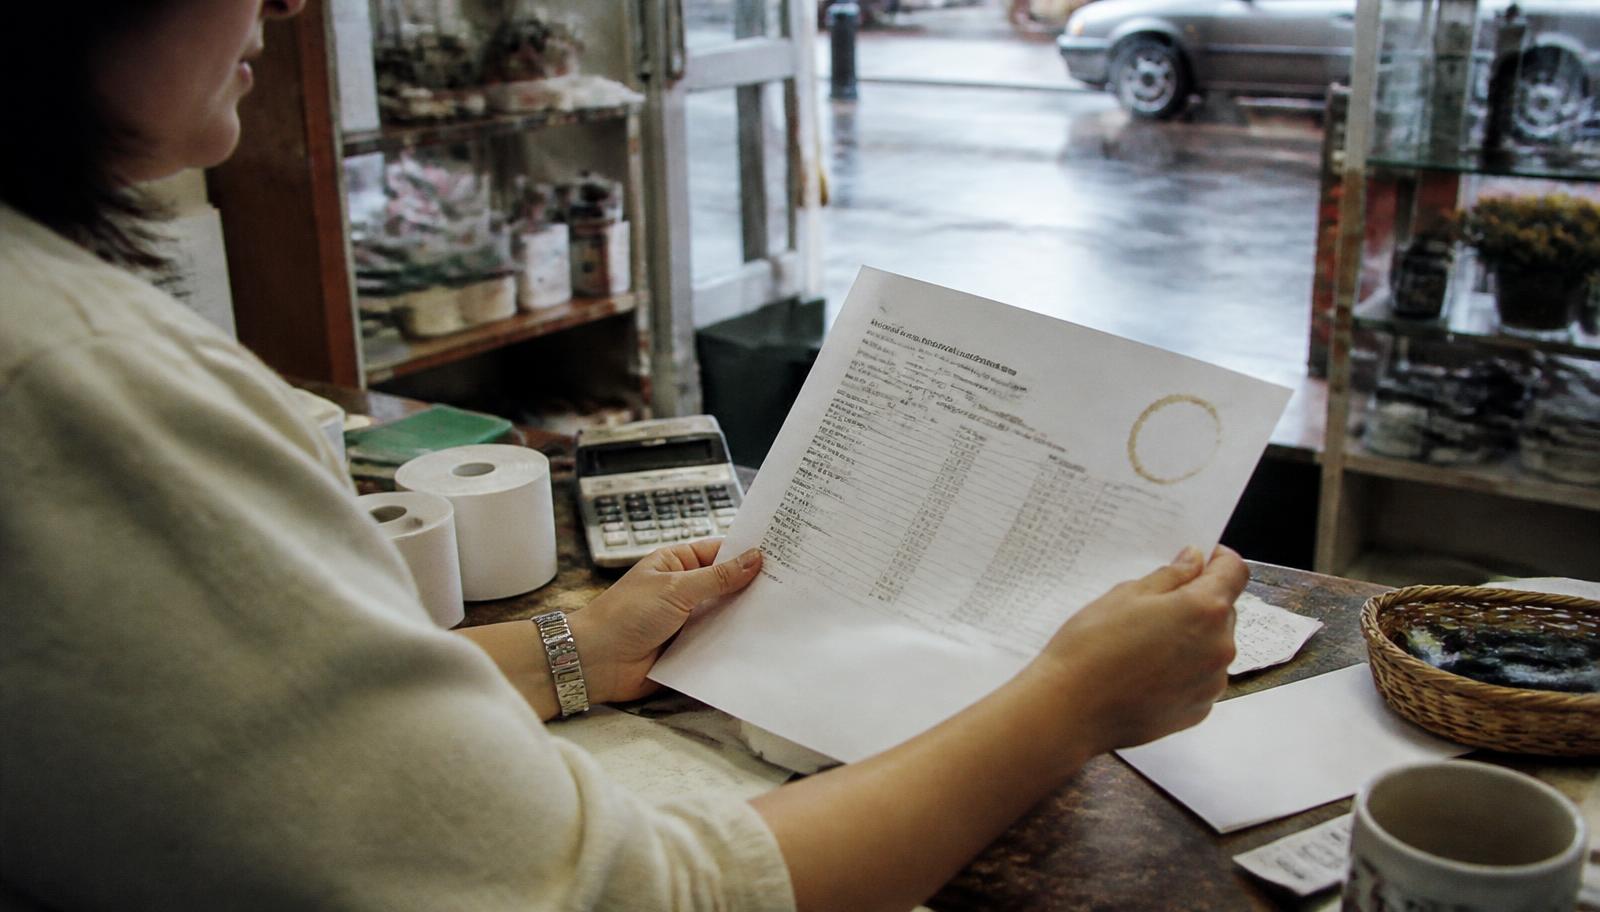
Most statements have a one-page summary near the front showing total volume, total fees, and an effective rate (total fees divided by total volume). That effective rate is the number that matters, not the rate you were quoted at signup.
- 1Find your total card sales volume for the month.
- 2Find your total fees charged for the month (add every line item, not just the discount rate).
- 3Divide fees by volume to get your true effective rate.
- 4Compare that number month to month, a rising trend means rate creep.
- 5Circle every fee that isn't a percentage of a sale (those are the flat junk fees).
- 6Call and ask about anything you can't explain.
If your statement doesn't have a clear summary page, or the fee categories are vague, that's itself a warning sign. For a step-by-step look at getting your rate down once you've found the padding, see how to lower your credit card processing fees.
Which fees are actually negotiable
- Statement fees and annual fees, almost always negotiable, and often waived just for asking.
- PCI non-compliance fees, eliminated entirely by completing the annual PCI questionnaire, no negotiation needed.
- Monthly minimum fees, avoidable by switching to a pricing plan that fits your actual volume.
- Batch fees, small, but worth asking about if you batch out daily.
- Markup on interchange-plus pricing, this is the real negotiation lever, since it's pure processor profit.
- Early termination fees, not negotiable after the fact, but avoidable by refusing long contracts up front.
PCI compliance deserves special attention because it's one of the few hidden fees that is completely within your control. It usually takes fifteen minutes once a year. Our guide to PCI compliance for small business walks through exactly what's required.
Zero-fee and surcharge programs, read the fine print
Some processors advertise 'zero-fee' or 'cash discount' programs that pass the cost of card acceptance to the customer instead of the merchant. These can genuinely eliminate your processing bill, but they come with rules about disclosure and state law that vary, and some vendors bundle in the same junk fees on top. We break down when this actually works in zero-fee credit card processing.
| Warning sign | What it usually means |
|---|---|
| Multiple fees you can't find defined in your contract | Invented line items with no real cost behind them |
| Your effective rate rose without a rate change notice | Interchange categories may be miscoded, or markup silently increased |
| Long contract with a steep early termination fee | Designed to make it expensive to compare or leave |
| Vague customer support answers about specific fees | A sign the rep either doesn't know or doesn't want to explain |
How to fix it without disrupting your business
You don't have to accept a padded statement, and you don't have to rip out your equipment to fix it. Most merchants can either negotiate directly with their current processor using a competing quote, or switch to a new provider without changing their day-to-day workflow. If you're considering a change, read how to switch payment processors first, it covers the parts people forget, like gift card balances and equipment compatibility.
Whether you keep your current processor or move, the goal is the same: know your real effective rate, strip out fees that don't reflect an actual cost, and get pricing that's transparent enough that you'd notice if it changed. That's the difference between a merchant account you can trust and one you have to audit every year.
Minnesota businesses
We review merchant statements for shops, restaurants and service businesses across Minneapolis, St. Paul and greater Minnesota at no cost, most reviews take about 20 minutes and tell you exactly where the padding is. We're a local team, not a call center, so if a question comes up later you can actually get someone on the phone.
Send us your last statement and we'll show you the real numbers. Book a free statement review or call 763-280-3155.
Frequently asked questions
Sources and references
Want this checked against your own statement?
Send us a recent processing statement and we'll mark it up line by line, what you're paying now, and what you'd pay with us. No pressure.